
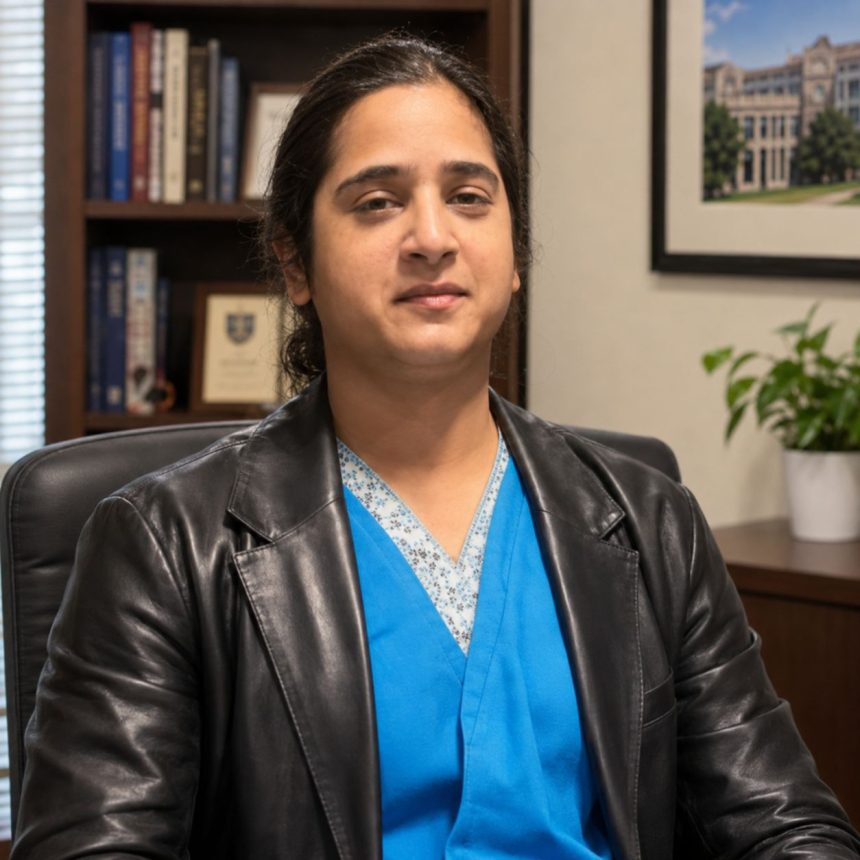
*Dr. Anum Shafique is a Lecturer and Researcher in Finance at PMAS-Arid Agriculture University, Rawalpindi : Published by ANI*
“Risk comes from not knowing what you’re doing.”
Warren Buffett
In today’s rapidly evolving financial landscape, Pakistan’s economic future depends not only on stronger banks or advanced digital technologies but also on financially informed citizens. Financial literacy is no longer merely a personal responsibility; it has become a national development priority. It equips individuals with the knowledge and confidence to make informed decisions about saving, borrowing, investing, and managing financial risks. Recognizing this, the State Bank of Pakistan (SBP) has placed financial literacy and consumer awareness at the heart of its National Financial Inclusion Strategy (NFIS) 2024-28.
The progress made over the past decade is encouraging. In 2015, only 16 percent of Pakistani adults had a bank account. By 2023, this figure had risen to 64 percent, reflecting a remarkable transformation in the country’s financial landscape. Millions of Pakistanis have entered the formal financial system in less than a decade-a significant achievement that demonstrates the impact of sustained policy reforms and technological innovation.
Women’s financial inclusion has also witnessed remarkable progress. In 2018, approximately 13 million women had bank accounts. By 2023, this number had increased to 31 million, while the gender gap in financial inclusion declined from 47 percent to 34 percent. These figures are more than just statistics; they represent greater economic participation, financial independence, and empowerment for millions of Pakistani women.
Equally significant is the fact that SBP’s vision extends far beyond increasing the number of bank accounts. While the central bank is widely known for maintaining monetary stability and controlling inflation, it has also assumed a leading role in promoting financial inclusion and consumer empowerment. Through initiatives such as the National Financial Literacy Program, Sikka Bakaida, the Banking on Equality Policy, consumer protection campaigns, digital financial literacy initiatives, awareness programmes for women and youth, outreach in rural communities, and financial education initiatives in schools and colleges, SBP has demonstrated a comprehensive commitment to building a financially informed society. Collectively, these initiatives have already reached approximately 3.2 million beneficiaries, of whom 58 percent are women.
Pakistan is also witnessing rapid growth in digital financial services through initiatives such as Raast, QR-code payments, mobile wallets, Asaan Mobile Accounts, and digital banking platforms. These innovations are making financial services faster, more convenient, and more accessible than ever before. However, technological advancement alone cannot guarantee meaningful financial inclusion. People must also understand how to use these services safely and responsibly. Financial literacy enables citizens to identify online scams, phishing attempts, account hacking, digital fraud, and fake investment schemes, ensuringthat technological progress translates into genuine financial security rather than new forms of vulnerability.
Looking ahead, financial literacy should become an integral part of Pakistan’s education system-not as an optional subject but as a core life skill. Schools and universities should prepare students not only for employment but also for responsible financial decision-making. Teaching young people how to budget, save, invest, understand digital payments, and protect themselves against financial fraud will better prepare them for the realities of modern life. Stronger partnerships among educational institutions, financial regulators, and the banking industry can also promote youth entrepreneurship and support the country’s growing digital economy. The NFIS itself recognizes the importance of integrating financial literacy into the national curriculum and strengthening collaboration with universities and other educational institutions.
Ultimately, financial literacy is about much more than banking. It is a fundamental life skill that enables individuals to save wisely, avoid excessive debt, recognize financial fraud, use digital payment systems securely, start businesses, plan for retirement, and make informed financial decisions throughout every stage of life. A financially literate citizen is not only better equipped to manage personal finances but also contributes to a stronger, more resilient national economy.
The progress achieved so far deserves recognition, but the journey towards universal financial inclusion is far from complete. Government institutions, educational institutions, financial organizations, the private sector, and civil society must work together rather than in isolation. Financial inclusion begins with access, but it succeeds only when access is accompanied by awareness. By investing in financial literacy today, Pakistan is not merely creating bank account holders-it is nurturing financially confident citizens who can actively contribute to inclusive and sustainable economic growth.

A well written article highlighting the importance of financial inclusion and literacy
Need more articles like this
The way you explained everything was perfect. So proud of you!
Much appreciated , wonderful article!
Knowledge is the most valuable investment anyone can make. Great job, Mam 👏 🙂
Best teacher in the world.
“Proud to be your student ,Ma’am.your dedication and passion for finance are truly inspiring.”🥰
” Teaching…. people how to budget, save, invest, understand digital payments, and protect themselves against financial fraud” ….. This for me is the best definition of financial literacy training.
Thanks Dr. Anum
Very inspiring and informative article madam.